 404.445.7885


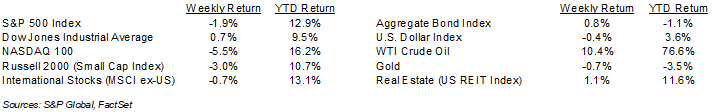
Technology stocks, especially those levered to the artificial intelligence buildout, weighed on equity markets last week. For the week, the S&P 500 Index declined 1.9%, the Dow Jones Industrial Average rose 0.7%, and the NASDAQ 100 fell 5.5%. The Consumer Staples, Energy, and Health Care sectors led the S&P 500 Index for the week, while Technology, Consumer Discretionary, and Communication Services lagged. The 10-year U.S. Treasury note yield ended Friday at 5.083%, down from 5.241% the previous week.
Inflation reports showed no significant abatement in price levels with the September Consumer Price Index (CPI) 0.4% higher month-over-month and core CPI, which excludes the impact of food and energy prices, 0.3% higher month-over-month. Year-over-year, headline CPI increased 3.7% and core CPI rose 2.6%. Gasoline prices were a significant contributor, increasing 9.1% month-over-month and 34.2% year-over-year. Producer prices were also elevated with the September Producer Price Index (PPI) rising 1.3% month-over-month and core PPI 0.5% higher. Year-over-year, headline PPI rose 6.3% and core PPI rose 5.0%.
CME fed funds futures indicate that investors expect the Federal Reserve to hold rates steady at its October policy meeting, followed by a 25-basis point increase in the federal funds target range at its December meeting.
The quarterly earnings reporting pace accelerates this week with 79 companies in the S&P 500 Index scheduled to report third-quarter results. Third-quarter earnings are expected to grow 29.0% year-over-year, with revenue growth of 12.6%. Full-year 2026 earnings are expected to grow 32.8%, with revenue growth of 12.7%.
In our Dissecting Headlines section, we look at the upcoming U.S. midterm election.
Financial Market Update
Dissecting Headlines: Midterm Elections
The U.S. midterm elections will be held on November 3rd. Early voting has already started in approximately 30 states. The Republican Party currently holds a narrow majority in the House of Representatives, 218 to 214. One Independent Representative caucuses with the Republicans and two seats are currently vacant. This narrow margin makes this election consequential for control of the House. Republicans also hold a small majority in the Senate, 53 to 47, including two Independents who caucus with the Democrats. Senate terms are staggered, and 35 seats are up for election next month, 22 Republican-held seats and 13 Democratic-held seats.
In the nineteen midterm elections since 1950, control of the House has changed six times, while the majority party has maintained control thirteen times. Most recently, Republicans gained control of the House from Democrats in the 2022 midterms. In the six times when control changed at the midterms, the S&P 500 Index rose an average of 16.1% over the following 12 months. In the thirteen times control was maintained by the majority party, the S&P 500 Index rose an average of 14.7%.
With Republican President Donald Trump in the White House and Republicans holding a larger majority in the Senate, control of the House could determine the direction of policy for the next two years. If Republicans maintain control of the House, we expect a continuation of policy on tax, energy independence, tariffs and trade, and deregulation. If Democrats take control, the divided government could result in greater opposition to the current Republican agenda and gridlock on significant legislative initiatives.
While election outcomes can impact policy and impact specific industries, investors should continue to focus on corporate earnings, economic growth, interest rates, and inflation, as these factors are more likely to drive investment returns.
________________________________________
Want a printable version of this report? Click here: NovaPoint Weekly October 19, 2026
To learn more about these topics and our investment strategies, call us at 404-445-7885 or contact us here.
Do you understand your personal investment risk tolerance and the risk of your current portfolio? You can learn these by taking our Risk Analysis Questionnaire.