 404.445.7885


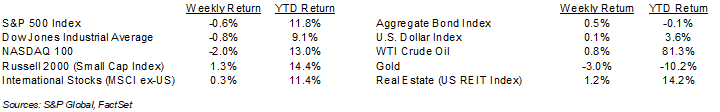
Underperformance in technology-related stocks and a shift toward more defensive sectors were evident last week. For the week, the S&P 500 Index declined 0.6%, the Dow Jones Industrial Average fell 0.8%, and the NASDAQ 100 fell 2.0%. The Health Care, Utilities, and Materials sectors led the S&P 500 Index for the week, while Communication Services, Technology, and Consumer Discretionary lagged. The 10-year U.S. Treasury note yield ended Friday at 4.910%, down from 4.998% the previous week.
The Fed held short-term interest rates steady at its October policy meeting. The FOMC voted 10-2 to maintain the federal funds target range at 3.75% to 4.00%, with two dissenters preferring a 25-basis-point increase. Current CME Fed funds futures point to a 25-basis-point increase at the December meeting and an additional 25-basis-point increase at the March meeting.
The advance estimate of third-quarter GDP showed annualized growth of 3.4%, up from 2.2% in the second quarter. Strong growth in personal consumption and fixed investment was partially offset by a drag from net exports. This week’s economic calendar includes the October Employment Situation report scheduled for Friday.
About 60% of the companies in the S&P 500 Index have reported third-quarter results, and another 140 companies are scheduled to report results this week. Third-quarter earnings are expected to grow 30.2% year-over-year, with revenue growth of 13.4%. For full-year 2026, earnings are expected to grow 32.9%, with revenue growth of 13.0%.
In our Dissecting Headlines section, we look at the components of GDP growth.
Financial Market Update
Dissecting Headlines: Third Quarter GDP
The U.S. economy grew at a 3.4% annualized rate in the third quarter, accelerating from 2.2% in the second quarter.
Consumer spending accounted for about three-quarters of GDP growth, with services spending growing 4.1% and goods spending increasing 3.0%. Hospitals, outpatient care, and restaurant meals were leading contributors within services, while prescription drugs led the increase in goods spending.
Private domestic investment grew 19.4%. Within investment, spending on information processing equipment rose 37.4%, software investment increased 9.6%, and research and development spending grew 7.5%. This strength aligns with the announcements from companies spending on the AI buildout. In contrast, housing investment declined 3.3%.
Trade subtracted from economic growth as exports declined 5.7% and imports increased 19.7%. Lower U.S. petroleum exports were a factor in the export decline. Capital goods, including computers and peripheral equipment, contributed to the increase in imports.
Government spending increased 5.3%, with federal spending increasing 15.8%, including an 11.7% increase in defense spending. State and local government spending declined 0.1%.
Overall, resilient consumer demand and strong business investment led growth, while weakness in housing and exports tempered expansion.
________________________________________
Want a printable version of this report? Click here: NovaPoint Weekly November 2, 2026
To learn more about these topics and our investment strategies, call us at 404-445-7885 or contact us here.
Do you understand your personal investment risk tolerance and the risk of your current portfolio? You can learn these by taking our Risk Analysis Questionnaire.