 404.445.7885


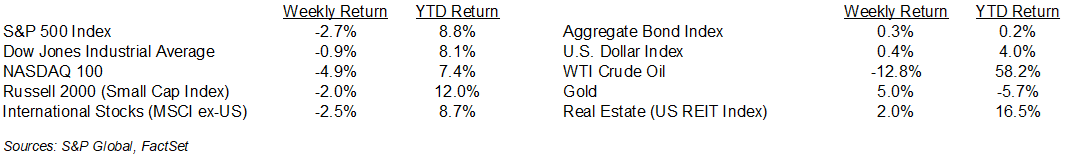
Volatility around election results and potential policy shifts contributed to equity market losses last week. For the week, the S&P 500 Index declined 2.7%, the Dow Jones Industrial Average fell 0.9%, and the NASDAQ 100 fell 4.9%. The Consumer Discretionary, Communication Services, and Real Estate sectors led the S&P 500 Index for the week, while the Energy, Technology, and Industrials lagged. The 10-year U.S. Treasury note yield ended Friday at 4.861%, down from 4.910% the previous week.
A stronger than expected employment report helped support a modest rebound on Friday following Thursday’s decline. The October Employment Situation report showed a gain of 165,000 jobs versus expectations for a gain of 65,000 jobs. September job gains were revised upward by 31,000 to a 60,000 net gain and August job gains were revised upward by 24,000 to 186,000. The October unemployment rate declined to 4.1% from 4.2% in September.
Current CME Fed funds futures show a 25-basis-point increase at the December policy meeting, consistent with the projected policy path from the September meeting. No additional rate increases are currently anticipated for the first two meetings of 2027.
About 88% of the companies in the S&P 500 Index have reported third-quarter results, and another 13 companies are scheduled to report results this week. Third-quarter earnings are expected to grow 31.4% year-over-year, with revenue growth of 14.3%. For full-year 2026, earnings are expected to grow 33.3%, with revenue growth of 13.2%.
In our Dissecting Headlines section, we look at the markets after the midterms.
Financial Market Update
Dissecting Headlines: Markets after Midterms
The Democratic Party secured enough seats to take control of both the U.S. House of Representatives and the U.S. Senate at last week’s midterm elections. Based on the latest available count, Democrats have won 254 seats in the House versus 164 for the Republicans, with 17 races still uncalled. In the Senate, the Democrats hold 54 seats, including two independents who caucus with the Democrats, versus 44 for Republicans. Two Senate races remain undecided.
The S&P 500 Index rose the day following the election, potentially reflecting reduced uncertainty as the outcome was decided on election day rather than a prolonged counting process. Technology stocks came under pressure on Thursday as investors considered the potential for stricter regulation of AI and data centers following comments from several winning candidates. The divided government with a Republican president and no Democratic super-majority in the Senate will likely result in cooperation in some areas and legislative gridlock in others. Without unified government, the chance of extreme policy change is lower.
Historically, stocks have performed well following midterm elections. Data on S&P 500 Index returns shows an average price return of 15.1% since 1950 in the twelve months following a midterm election with a positive return in all 19 periods.
Fiscal policy will remain important. Budgets and borrowing impact the national debt and longer-term interest rates. Spending priorities can benefit some industries and create challenges for others, as well as impact inflation and job growth. Still, less extreme moves by the government allow investors to focus on fundamentals of businesses and their earnings growth.
________________________________________
Want a printable version of this report? Click here: NovaPoint Weekly November 9, 2026
To learn more about these topics and our investment strategies, call us at 404-445-7885 or contact us here.
Do you understand your personal investment risk tolerance and the risk of your current portfolio? You can learn these by taking our Risk Analysis Questionnaire.