 404.445.7885


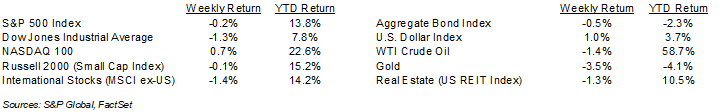
Equities rose Friday following a subdued employment report, but the S&P 500 and Dow still finished lower for the week. For the week, the S&P 500 Index fell 0.2%, the Dow Jones Industrial Average fell 1.3%, and the NASDAQ 100 gained 0.7%. The Technology, Energy, and Utilities sectors led the S&P 500 Index for the week, while Health Care, Financials, and Consumer Staples lagged. The 10-year U.S. Treasury note yield was 5.278% at Friday’s close, versus 5.160% the previous week.
The economy added 29,000 jobs in September versus the expectation for 90,000 jobs, and the unemployment rate rose to 4.2% versus 4.1% in August. The softer report eased some pressure on the Federal Reserve to raise the fed funds rate at its October policy meeting. August payroll growth was revised down by 29,000 to a gain of 133,000, while July payrolls were revised down by 31,000 to a loss of 10,000. CME fed funds futures now price in a single 0.25% increase by the December meeting, compared with increases at both remaining meetings earlier.
This week, four companies in the S&P 500 Index are scheduled to report third-quarter earnings. Third-quarter earnings are expected to grow 29.5% year-over-year, with revenue growth of 12.3%. Full-year 2026 earnings are expected to grow 32.4%, with revenue growth of 12.4%.
In our Dissecting Headlines section, we look at the upcoming third quarter earnings season.
Financial Market Update
Dissecting Headlines: Third Quarter Earnings
The early part of the third quarter earnings season kicks off this week. According to FactSet, S&P 500 Index earnings are forecast to grow 29.5% year-over-year, with all eleven sectors expected to report growth. Higher oil prices are expected to drive Energy sector earnings growth of 114.0%. The Technology sector follows at 65.0%, then Communication Services at 51.5%, both benefiting from spending on artificial intelligence. The eight remaining sectors are expected to grow, but below the overall Index level. These are the Materials sector at 29.4%, Industrials at 14.6%, Real Estate at 8.7%, Utilities at 6.9%, Health Care at 5.5%, Consumer Discretionary at 3.2%, Financials at 3.0%, and Consumer Staples at 2.9%.
S&P 500 Index revenue is forecast to grow 12.3% year-over-year. Technology is expected to lead at 40.5%, followed by Energy at 21.4% and Communication Services at 15.4%. The remaining eight sectors are forecast to report revenue growth, but below the overall Index level with Real Estate at 9.8%, Utilities at 9.4%, Industrials at 9.1%, Materials at 8.8%, Financials at 7.3%, Consumer Staples at 5.9%, Consumer Discretionary at 5.0%, and Health Care at 4.0%.
How companies perform relative to these expectations, and what management teams say about their outlooks, should determine stock price performance. Commentary on energy prices, inflation, hiring plans, and the adoption of artificial intelligence should also give a clearer picture of where the economy is headed.
________________________________________
Want a printable version of this report? Click here: NovaPoint Weekly October 5, 2026
To learn more about these topics and our investment strategies, call us at 404-445-7885 or contact us here.
Do you understand your personal investment risk tolerance and the risk of your current portfolio? You can learn these by taking our Risk Analysis Questionnaire.